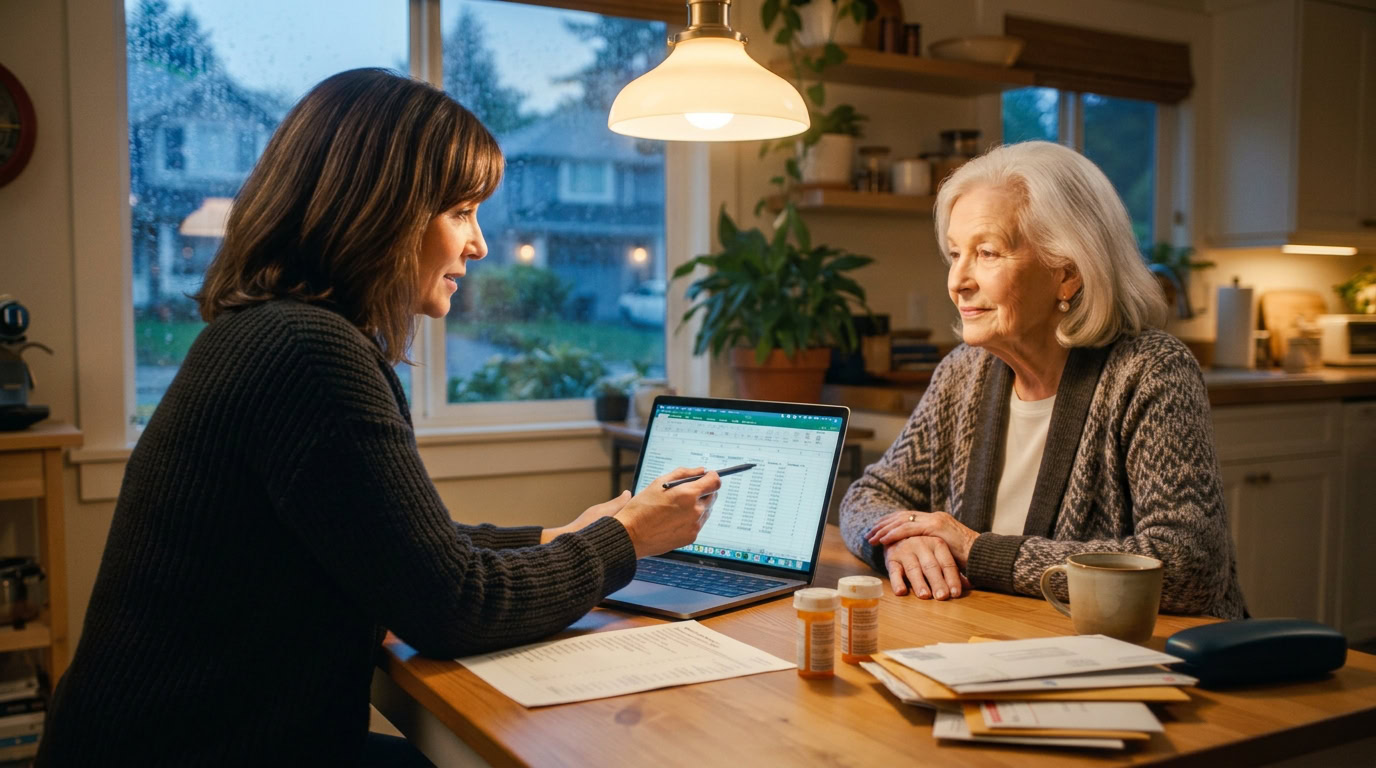
The envelope has been sitting on your mother’s kitchen counter for three weeks. It says “Annual Notice of Change” in small type, and under it is a stack of glossy mailers promising “$0 premiums” and “extra benefits.” Mom asks you, a little too casually, whether she should switch. You realize you have no idea what she has now.
You are not behind. Millions of adult children find themselves at this exact counter every fall. The good news is that the decision is manageable if you take it in order, and there is free, unbiased help available in every state.
Open enrollment runs from October 15 through December 7, 2026. Whatever your parent chooses takes effect January 1, 2027.
What actually changes for 2027?
The biggest changes are in prescription drug coverage. The yearly cap on what a person pays out of pocket for covered Part D drugs rises to $2,400, up from $2,100. The standard Part D deductible rises from $615 to $700. Medicare-negotiated prices also take effect for 15 more drugs, including Ozempic and Wegovy, according to the Associated Press.
Plans themselves change every year too. A drug plan can drop a medication from its list, a Medicare Advantage plan can leave a doctor’s network, and premiums and copays move. That is why the Annual Notice of Change matters. It is the plan telling your parent, in writing, what will be different in January.
Should my parent switch plans at all?
Not necessarily. Staying put is a perfectly good outcome, as long as you have checked. The question to answer is simple: will your parent’s current plan still cover their medications, their doctors, and their pharmacy next year at a cost they can manage? If yes, there may be no reason to move.
Here is the order I suggest:
- Find the current plan card and the Annual Notice of Change. Read the summary page for changes to premiums, drug coverage, and doctors.
- Make a complete medication list. Name, dose, and how often. Pull the bottles out of the cabinet if you need to. This list does more work than anything else in the process.
- List the doctors and the hospital your parent wants to keep.
- Run the numbers on Medicare Plan Finder. Enter the drugs and pharmacy, and it shows estimated yearly costs plan by plan. Look at the total for the year, not just the monthly premium.
In the book I call this kind of homework caregiving literacy. You don’t need to become a Medicare expert. You need to know enough to ask the right question at the right time.
What is the difference between Original Medicare and Medicare Advantage?
Original Medicare is the federal program: Part A for hospital care and Part B for doctors and outpatient care, usually paired with a Part D drug plan and often a Medigap supplement. Medicare Advantage is a private plan that bundles those benefits, usually with a provider network and sometimes extras like dental or vision.
Neither is right for everyone. Original Medicare with a Medigap policy tends to mean higher premiums but fewer surprises and the freedom to see any doctor who takes Medicare. Medicare Advantage often means lower premiums, but networks, prior authorization, and copays that can add up during a hospital stay or rehab.
One caution worth knowing before your parent switches from Medicare Advantage back to Original Medicare: in most states, Medigap insurers can ask health questions and charge more or decline coverage outside of certain protected windows. If your parent’s health has changed, talk to a counselor before moving.
Where can we get free, unbiased help?
Every state has a State Health Insurance Assistance Program, known as SHIP. SHIP counselors are trained, free, and do not sell insurance. They can sit down with you and your parent, by phone or in person, and walk through the options. Find your state’s program at shiphelp.org or through the Eldercare Locator at 1-800-677-1116.
You can also call 1-800-MEDICARE (1-800-633-4227), any time of day.
Be careful with the glossy mailers and the television ads. Many come from brokers or marketers paid by plans. They are not necessarily wrong, but they are not neutral either. A SHIP counselor is.
Can I talk to Medicare on my parent’s behalf?
Yes, with permission. Your parent can be on the line and give verbal consent, or fill out the “Authorization to Disclose Personal Health Information” form so Medicare can speak with you directly. Find it on Medicare.gov. This is worth doing now, before a hospital stay or billing problem makes it urgent.
If your parent has limited income and savings, also check whether they qualify for Extra Help, which lowers drug costs. Many people who qualify never apply.
Common questions
What happens if we miss December 7?
In most cases your parent keeps their current coverage for 2027. Someone in a Medicare Advantage plan gets a second chance from January 1 through March 31 to switch plans once or return to Original Medicare. Certain life events, like a move, also open special enrollment periods.
My mom says her plan is fine. Do I need to push?
You don’t need to push. You can offer to check the medication list against next year’s coverage together. Framed as “let’s make sure nothing changed,” most parents welcome the help.
Is a $0 premium plan a good deal?
Sometimes. A $0 premium tells you nothing about deductibles, copays, or whether the doctors your parent sees are in the network. Compare the estimated total yearly cost on Plan Finder.
Do I need power of attorney to help with Medicare?
Not for enrollment if your parent can make the decision and give consent. If your parent can no longer manage their own affairs, a durable power of attorney becomes important. See our glossary entry on power of attorney.
Keep going
Open enrollment is one of the few caregiving deadlines that arrives with a calendar date attached. Use it. Sit down with your parent, a medication list, and a cup of coffee, and get it done before the holidays crowd everything else out.
For more on the money side of caregiving, see the Caregiving Finances pillar and our financial and legal resources.
Ron Roel
Free chapter: “Caring for the Caregiver” from Ron’s book, The CareGiving Navigator
The part most people skip, and shouldn’t. Send Ron’s chapter to your inbox.
Sources
- Associated Press via PBS NewsHour: Medicare open enrollment starts now. These changes will arrive in 2027 (Oct. 15, 2026)
- Medicare.gov: Medicare Plan Finder
- Medicare.gov: Authorization to Disclose Personal Health Information (CMS-10106)
- SHIP National Technical Assistance Center: Find your local SHIP
- Social Security Administration: Extra Help with Medicare prescription drug costs
- Eldercare Locator, U.S. Administration for Community Living